Financial technology has transformed how people access money, make payments, and manage their financial lives. From automated banking terminals to mobile applications, online account portals, and digital payment systems, solutions such as Bankomat have made many routine tasks faster and more convenient. Yet as these services become increasingly connected, protecting personal information and maintaining trust have become just as important as improving convenience.
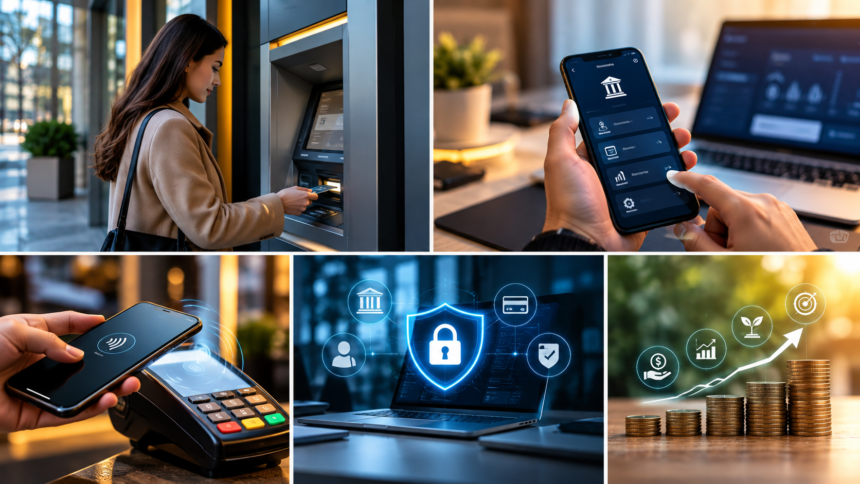
Bankomat is a term commonly associated with automated banking machines that allow customers to access selected financial services without visiting a traditional branch. These machines illustrate how physical banking infrastructure continues to operate alongside modern digital platforms. A customer may withdraw cash from a terminal, review the transaction through a mobile application, and receive an account notification within minutes. Each interaction depends on technology that must process information accurately and protect it from unauthorized access.
Financial technology also raises important questions about privacy and digital identity. Customers need to know how their information is collected, who can access it, and whether the services they use are legitimate. A name such as Bankomat.cc should therefore be evaluated in its specific context rather than automatically assumed to represent an authorized banking provider.
Understanding the relationship between financial technology, privacy, and digital trust helps consumers make informed decisions. It also helps financial institutions design services that combine convenience with dependable security and responsible data management.
Understanding Bankomat and Modern Financial Technology
Financial technology, often called fintech, includes the digital tools and systems used to deliver, manage, and improve financial services. It ranges from mobile banking applications and electronic payment networks to automated terminals, fraud-monitoring systems, and digital identity verification.
Bankomat fits into this broader environment through its association with automated banking. Traditional ATMs made cash withdrawals and basic account services available beyond standard branch hours. Over time, many machines gained additional functions, including supported deposits, balance inquiries, transfers, and other self-service transactions.
The underlying technology is more complex than the physical machine suggests. A transaction may require card or account verification, communication with a financial network, authorization from the relevant institution, and an accurate update to the customer’s account records. Security controls must protect each stage against unauthorized access and processing errors.
Modern financial technology extends these capabilities by connecting physical services with digital channels. Customers can manage cards through applications, monitor account activity online, and receive alerts when certain transactions occur. These connected experiences reduce the need to visit branches for routine tasks while giving customers more visibility into their finances.
However, technology should solve practical problems rather than introduce unnecessary complexity. An effective banking service must be easy to use, dependable, accessible, and transparent about its limitations. Innovation becomes valuable when it helps customers complete financial activities confidently without compromising privacy or security.
Why Digital Trust Matters in Financial Services
Trust is fundamental to financial relationships. Customers expect their banks to safeguard their money, process transactions correctly, and protect information that could expose them to fraud or identity misuse. When these expectations are not met, the consequences can extend beyond a single transaction.
A security incident may result in unauthorized payments, account access problems, or the exposure of personal information. Customers may need to replace cards, reset passwords, contact support teams, and monitor their accounts for further suspicious activity. For financial institutions, incidents can also create operational costs, regulatory obligations, and reputational damage.
Digital trust depends on several factors working together. Technical safeguards protect systems, clear communication helps customers understand services, and effective support provides a way to resolve problems. Transparency matters because customers need to understand what a service does and how their information is handled.
Financial institutions should also recognize that trust is built through repeated experiences. Accurate transaction records, reliable service availability, understandable fees, and prompt responses to customer concerns all contribute to confidence. A single security feature cannot compensate for persistent failures in these areas.
For customers, trust should not mean accepting every online claim without question. Even when a website looks professional or uses familiar financial terminology, its identity should be verified independently before sensitive information is shared.
Financial Privacy and the Responsible Use of Personal Data
Financial privacy concerns the collection, use, storage, and sharing of information associated with a person’s financial activities. This information may include account details, transaction histories, contact information, identification documents, and payment records.
Banks need certain data to authorize transactions, provide services, detect suspicious activity, and meet legal requirements. The challenge is ensuring that information is used for legitimate purposes and protected against unnecessary exposure.
One important principle is data minimization. Organizations should collect only the information required for a defined purpose and retain it only as long as justified. Reducing unnecessary data collection can limit the potential harm if a system is compromised.
Access controls are equally important. Employees and service providers should receive access only to the information required for their responsibilities. Sensitive records should be protected through appropriate security measures, and organizations should maintain procedures for reviewing access and addressing unauthorized activity.
Customers can contribute to their own privacy by limiting the information they share online. Avoid sending identification documents through unverified channels, be cautious when granting application permissions, and review privacy settings on devices and financial applications. If a service requests information that appears unrelated to its purpose, seek clarification before proceeding.
Clear privacy policies also help establish trust. They should explain what information is collected, why it is needed, how it is protected, and when it may be shared. These explanations should be understandable to ordinary customers rather than hidden behind unnecessarily complicated language.
Bankomat.cc and the Importance of Verifying Online Identity
Online banking depends on customers being able to identify legitimate services. Unfortunately, familiar names and financial terminology can also appear on websites that have no verified connection to an established institution.
Bankomat.cc should be assessed according to its specific context. The domain name alone does not establish that it belongs to a bank, an authorized ATM operator, or a regulated financial provider. Before interacting with an unfamiliar financial website, users should independently establish who operates it and what services it actually provides.
Begin by checking whether the relevant institution identifies the website through its official channels. Review the operator’s stated identity, contact information, privacy policy, and terms of service. Where appropriate, consult the relevant financial regulator’s public information to determine whether the organization is authorized to provide the claimed services.
Be cautious if a website requests bank credentials, payment-card information, identity documents, or verification codes without a clear and verifiable reason. Avoid downloading unexplained files or making payments through a service whose legitimacy remains uncertain.
A secure connection is not enough to establish trust. HTTPS encrypts communication between a browser and a website, but deceptive websites can use encryption too. Users must evaluate the website’s identity, purpose, and credibility rather than relying on a single technical indicator.
For routine financial activities, use a verified banking application, a known official website, or customer-support details obtained independently. These channels provide a safer starting point than links received through unexpected messages or unfamiliar online discussions.
Cybersecurity Risks Facing Digital Banking
As financial services become more connected, cybercriminals have more opportunities to target accounts, devices, and information. Common threats include phishing, credential theft, malicious applications, social engineering, and attempts to exploit software vulnerabilities.
Phishing often begins with a message that appears to come from a bank or payment provider. It may warn that an account has been restricted, claim that a transaction needs confirmation, or ask the recipient to verify personal details. The message typically directs the user to a page designed to collect sensitive information.
Social engineering uses a different but related approach: manipulating people into taking actions that compromise their security. An attacker may impersonate a support employee, create a false sense of urgency, or request a verification code under the pretense of helping resolve an account problem.
Automated banking terminals face additional risks because they combine physical equipment with connected financial systems. Operators need to inspect machines for suspicious modifications, maintain secure software, restrict access to sensitive components, and monitor unusual transaction activity.
Customers should adopt a consistent set of protective habits:
- Use unique, strong passwords for important financial accounts.
- Enable multi-factor authentication wherever available.
- Keep devices and banking applications updated.
- Review account activity and activate transaction notifications.
- Never disclose passwords, PINs, or one-time verification codes to unsolicited callers or messages.
- Report unfamiliar transactions and suspected account compromise promptly.
Financial institutions should complement these habits with encryption, secure authentication, vulnerability management, access restrictions, and tested incident-response procedures. Security works best when technology and informed customer behavior reinforce one another.
Artificial Intelligence and Smarter Fraud Detection
Artificial intelligence is increasingly used to help financial institutions identify suspicious activity and manage large volumes of transactions. Automated systems can analyze patterns, compare current behavior with previous activity, and flag transactions that warrant further examination.
For example, a transaction that differs substantially from a customer’s usual activity may trigger additional verification. This does not automatically mean the transaction is fraudulent; it simply provides a signal that the bank may need to investigate.
AI can also help identify recurring patterns across multiple accounts, support customer-service systems, and predict when certain pieces of banking equipment may require maintenance. These applications can improve efficiency when implemented with appropriate safeguards.
However, automated systems can make mistakes. Legitimate transactions may be flagged incorrectly, while unfamiliar forms of fraud may go undetected. Financial institutions need regular testing, human oversight, and clear procedures for correcting inaccurate decisions.
Privacy must remain a priority as well. Banks should evaluate what information their systems require, restrict access appropriately, and explain consequential decisions to customers when possible. Automation should strengthen responsible financial management rather than create an opaque system that customers cannot challenge.
The future of Bankomat-related services may include better equipment monitoring, more responsive fraud detection, and improved integration with digital banking applications. The goal should be to improve reliability and security while preserving customer control.
Secure Payments and the Evolution of Banking Access
Payment technology has expanded beyond cash withdrawals and traditional card transactions. Contactless cards, digital wallets, mobile payment applications, and faster transfer networks now give customers additional ways to move money and complete purchases.
Digital wallets can store supported payment credentials on compatible devices, while some payment systems use tokenization to reduce exposure of underlying card details. Depending on the provider, authentication may involve a device passcode, fingerprint, facial recognition, or another supported security method.
These developments can make payments faster, but customers still need clear information about fees, transaction limits, and dispute procedures. If a phone or card is lost, they should know how to block access and contact the provider.
Physical banking infrastructure remains relevant within this changing environment. Many people continue to need cash, and not every location has dependable digital payment coverage. Automated terminals can therefore complement online banking rather than compete with it.
The strongest financial ecosystems provide multiple ways to access services. Customers should be able to choose a suitable channel while receiving consistent account information and appropriate security protections across the entire experience.
Financial Inclusion and Responsible Innovation
Technology can improve access to financial services for people who live far from bank branches or have limited time to visit them. Automated terminals and mobile applications can reduce travel, simplify routine transactions, and help small businesses manage their finances.
However, digital access is not universal. Some people lack reliable internet connections, suitable devices, or the confidence to use unfamiliar applications. Others need accessible interfaces, multilingual support, or assistance from a human representative.
Financial institutions should design services around these differences. Offering several access channels, explaining fees clearly, and providing practical customer support can help prevent technological progress from excluding people who need financial services most.
Responsible innovation also requires attention to reliability. A new application or automated system should be tested carefully before it becomes central to customers’ financial lives. Banks should monitor performance, address recurring failures, and communicate clearly when a service becomes unavailable.
The success of financial technology should be measured by the value it provides to customers, not simply by the number of digital features introduced. Better access, stronger security, understandable processes, and dependable service are more meaningful outcomes than novelty alone.
How Financial Institutions Can Build Lasting Digital Trust
Financial institutions must treat security and privacy as ongoing responsibilities rather than one-time technical projects. Systems need regular updates, access reviews, security assessments, and appropriate oversight of third-party providers. Employees also require training to recognize suspicious activity and follow established procedures.
Transparency is equally important. Customers should be able to find official contact channels, understand how to report fraud, and learn what to do if their cards or accounts may have been compromised. Clear instructions can reduce confusion during stressful situations.
Institutions should also establish effective incident-response plans. When a potential breach occurs, they need to investigate the scope, contain affected systems, protect remaining information, and communicate with relevant parties according to applicable obligations.
Service quality should be evaluated through practical measures, including transaction accuracy, system availability, fraud detection effectiveness, accessibility, and the time required to resolve customer disputes. These indicators help organizations understand whether their technology is delivering meaningful improvements.
Ultimately, digital trust emerges when secure systems, responsible data practices, and dependable customer support work together. Customers need confidence not only that a transaction will succeed, but also that the institution will respond appropriately when something goes wrong.
Conclusion
Bankomat and modern financial technology demonstrate how banking has evolved through the integration of automated terminals, digital payments, connected platforms, and advanced security systems. These developments have improved convenience and expanded access to financial services, but they have also increased the importance of protecting personal information and verifying digital identities.
Strong authentication, careful browsing, privacy-conscious data practices, and reliable fraud monitoring all contribute to safer financial experiences. Customers should use verified banking channels, review their transactions, and report suspicious activity promptly. Financial institutions must support these habits with secure infrastructure, clear communication, and effective incident response.
References such as Bankomat.cc also highlight why a familiar domain name should never replace independent verification. Customers deserve to know who operates a service before trusting it with sensitive information.
Digital finance earns trust when innovation remains accountable to the people it serves. By combining convenience with security, privacy, and transparent practices, financial institutions can build services that are not only easier to use but also more dependable and worthy of customer confidence.